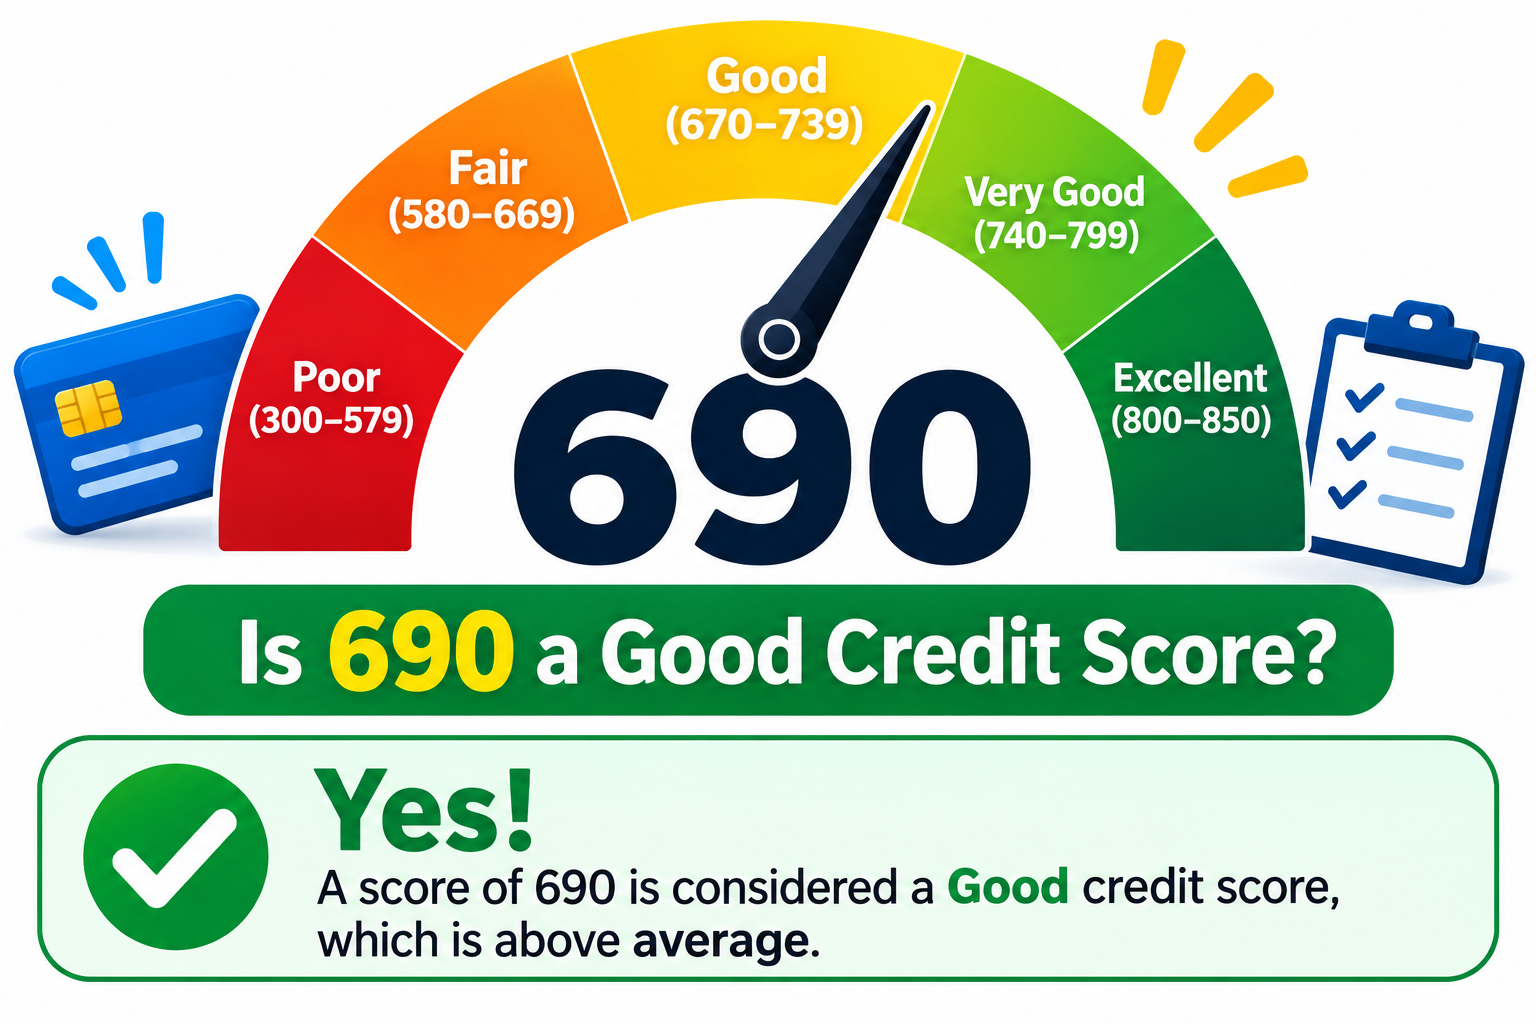
A 690 credit score is generally considered a good credit score under the two major credit scoring systems used in the United States. It indicates that you have a reasonably established credit profile and may be able to manage borrowed money responsibly. With this score, you may qualify for several financial products, including credit cards, auto loans, personal loans, and some mortgage programs.
However, having a good credit score does not automatically mean you will receive the lowest interest rates or qualify for every financial product. Lenders consider several factors when reviewing an application, including your income, employment history, outstanding debt, payment behavior, and the scoring model they use.
If your current score is 690, you are in a positive position, but there is still room for improvement. Moving toward 720, 740, or 780 could help you access more competitive financial offers. Understanding what a 690 score means, how lenders evaluate it, and which habits influence your credit profile can help you make better financial decisions.
Is 690 a Good Credit Score?
Yes, a 690 credit score is considered good under the standard FICO scoring model. FICO scores range from 300 to 850, and the good credit category covers scores from 670 to 739.
A score of 690 is above the fair credit range, which generally extends from 580 to 669. This means you have moved into a category that lenders commonly view more favorably than fair or poor credit.
VantageScore also classifies a 690 score as good under its commonly used models. Although FICO and VantageScore calculate scores differently, both recognize that a higher score generally indicates lower credit risk.
What does a 690 score mean for you?
- You may qualify for a variety of credit cards and loans.
- Some lenders may offer competitive borrowing terms.
- You may have better approval opportunities than applicants with fair or poor credit.
- You may still receive higher interest rates than borrowers with very good or excellent credit.
- Your approval chances will depend on your complete financial profile.
A 690 score is a good foundation for future financial goals. However, maintaining it is just as important as improving it. Missing payments, increasing credit card balances, or applying for several accounts within a short period could negatively affect your score.
Understanding Credit Score Ranges
Before deciding how good a 690 score is, it helps to understand the categories used by credit scoring companies.
The standard FICO scoring model uses a range of 300 to 850. Its general credit score categories are:
| FICO Score Range | Category |
| 300–579 | Poor |
| 580–669 | Fair |
| 670–739 | Good |
| 740–799 | Very Good |
| 800–850 | Exceptional |
A 690 score falls within the good category. It is 20 points above the beginning of the good range, which means there is an opportunity to move toward the very good category by reaching 740.
VantageScore 3.0 and 4.0 use different categories:
| VantageScore Range | Category |
| 300–600 | Poor |
| 601–660 | Fair |
| 661–780 | Good |
| 781–850 | Excellent |
Under these VantageScore models, 690 is also considered good.
Remember that your credit score may differ depending on the bureau and scoring model. A lender might use a particular FICO version, while a free credit monitoring service may display a VantageScore. This is one reason the score you check yourself may not match the number a lender uses.
Is a 690 Credit Score Good Enough for a Credit Card?
Yes, a 690 credit score can help you qualify for several types of credit cards. You may have access to cash-back cards, general-purpose cards, and some rewards products, depending on the issuer’s eligibility requirements.
However, premium travel cards and cards with extensive benefits may require a stronger credit profile. Card issuers also consider your income, existing debt, payment history, recent applications, and current credit limits.
Cash-back credit cards: Some issuers offer cards that provide cash back on groceries, gas, dining, and everyday purchases. A 690 score may put certain options within reach, although approval is never guaranteed.
Rewards credit cards: These cards may offer points or other benefits on eligible purchases. Compare annual fees, reward restrictions, and interest rates before applying.
Balance transfer cards: Some credit cards provide promotional interest rates for transferring existing balances. Approval depends on the issuer’s criteria, and transfer fees may apply.
Credit union cards: Credit unions sometimes offer credit card products to members with different credit profiles. Their eligibility requirements and benefits vary.
Before submitting an application, check whether the issuer provides prequalification. Prequalification generally uses a soft inquiry, which does not affect your credit score. A formal application may result in a hard inquiry.
Is 690 a Good Credit Score for Buying a Car?
A 690 credit score can be a good starting point when applying for an auto loan. Many lenders consider borrowers in this range, although the interest rate and loan conditions depend on the complete application.
Your credit score is only one part of the financing decision. Auto lenders may also review your income, employment stability, existing monthly payments, down payment, vehicle price, and loan term.
Auto loan interest rates: A 690 score may qualify you for financing, but your rate could be higher than the rate offered to someone with a 750 or 800 score. A higher annual percentage rate can increase the total interest paid over the life of the loan.
Down payment: Providing a larger down payment reduces the amount you need to borrow. It may also improve your overall financing position.
Loan term: A longer repayment period can make monthly payments smaller, but it may increase the total interest cost. Compare the full repayment amount rather than focusing only on the monthly payment.
Comparing lenders: Consider offers from banks, credit unions, and dealership financing departments. Comparing multiple offers can help you identify better terms.
When shopping for an auto loan, eligible applications submitted within a short period may be grouped for scoring purposes by certain FICO models. The applicable rate-shopping window varies by scoring version.
Can You Buy a House With a 690 Credit Score?
Yes, a 690 credit score may be sufficient for several mortgage programs in the United States. It is above the commonly cited minimum score for many conventional mortgage programs and may also meet the credit score requirements for FHA financing.
However, mortgage approval involves more than your credit score. Lenders usually review your income, employment history, debt-to-income ratio, savings, down payment, and the property you intend to purchase.
Conventional mortgages: Many conventional mortgage programs commonly require a minimum score around 620, although requirements vary by lender and program. A 690 score may meet the credit requirement, provided you satisfy the other conditions.
FHA loans: FHA-insured loans generally allow borrowers with scores of 580 or higher to qualify for maximum financing with a minimum down payment of 3.5%. Borrowers with scores between 500 and 579 generally need at least 10% down. Lender requirements may be stricter.
Mortgage interest rates: A 690 score may qualify you for financing, but a higher score could improve your pricing. The exact rate depends on the loan type, lender, market conditions, down payment, and other borrower characteristics.
Debt-to-income ratio: Lenders compare your monthly debt payments with your gross monthly income. A manageable debt-to-income ratio can strengthen your mortgage application.
If you are planning to purchase a home, compare mortgage offers and ask lenders which credit score model they use. Reviewing your reports before applying can also help you identify potential problems.
What Factors Affect a 690 Credit Score?
Your credit score is calculated using information from your credit reports. Traditional FICO scoring models consider five major categories.
1. Payment history
Payment history accounts for approximately 35% of a traditional FICO score. It reflects whether you pay your credit cards, loans, and other reported accounts on time.
Late payments, missed payments, collections, and serious delinquencies can negatively affect your credit profile.
To protect a 690 score, pay every account by its due date. Automatic payments and calendar reminders can help prevent accidental missed payments.
2. Credit utilization
Credit utilization is the percentage of your available revolving credit that you are currently using. It falls within the amounts-owed category, which represents approximately 30% of a traditional FICO score.
For example, if your total credit card limit is $10,000 and your outstanding balances are $2,000, your utilization is 20%.
Lower utilization is generally better for your score. Paying down balances and avoiding unnecessary spending can help keep this percentage manageable.
3. Length of credit history
The length of your credit history accounts for approximately 15% of a traditional FICO score. It considers how long your accounts have been open and the age of your oldest and newest accounts.
A longer history of responsible credit use can support your score. Avoid closing older accounts without considering how doing so could affect your available credit and overall credit profile.
4. New credit
New credit represents approximately 10% of a traditional FICO score. It considers recent applications and newly opened accounts.
Applying for several credit cards or loans within a short period can result in multiple hard inquiries. Apply only when you genuinely need additional credit.
5. Credit mix
Credit mix accounts for approximately 10% of a traditional FICO score. It considers the different types of credit accounts you manage, such as credit cards, auto loans, and mortgages.
You do not need to take out unnecessary loans to improve your credit mix. Responsible management of your existing accounts is more important.
These percentages are general FICO guidelines. The exact effect of each factor depends on your individual credit report and scoring model.
How to Improve a 690 Credit Score
Although 690 is a good score, improving it may help you qualify for better financial products and more competitive borrowing terms. The following habits can help you move toward 720, 740, or higher.
Pay every bill on time: Payment history is one of the most influential credit scoring factors. Make at least the required payment by the due date, and consider automatic payments to avoid forgetting important bills.
Reduce credit card balances: High credit card balances can increase your utilization ratio. Focus on paying down existing balances rather than opening additional accounts.
Keep credit utilization low: Many consumers aim to keep utilization below 30%, although lower utilization is generally preferable. You do not need to carry a balance or pay interest to build credit.
Avoid unnecessary applications: Every formal credit application may result in a hard inquiry. Research eligibility requirements and compare offers before applying.
Review your credit reports: Check your reports from Equifax, Experian, and TransUnion for incorrect account details, unfamiliar accounts, inaccurate late payments, or duplicate collection entries.
Dispute genuine errors: If you find incorrect information, you can dispute it with the credit bureau and the company that supplied the information. Disputing inaccurate information is free. Accurate negative information generally cannot be removed simply because it lowers your score.
Keep older accounts in good standing: Older accounts can contribute to the length of your credit history. If an account has no annual fee and remains useful, keeping it open may help preserve your available credit.
Monitor your progress: Check your credit reports and score periodically. Tracking changes can help you understand whether your financial habits are improving your credit profile.
How Long Does It Take to Improve a 690 Credit Score?
The time needed to improve a 690 score depends on what is affecting your credit history.
If high credit utilization is the main problem, reducing your credit card balances may help within one or two reporting cycles after the issuers update your account information.
If your score is affected by late payments, collections, or other negative information, improvement may take longer. Building a stronger payment history requires consistent behavior over time.
There is no guaranteed timeline for moving from 690 to 720 or 740. Some consumers may see progress within a few months, while others may need a year or longer.
Avoid companies that promise a specific number of credit score points within a few days. Sustainable improvement generally comes from paying on time, managing debt, correcting genuine reporting errors, and using credit responsibly.
Is 690 Below the Average U.S. Credit Score?
Yes, a 690 FICO score is below the reported U.S. national average. FICO reported an average score of 714 in July 2026.
However, being below average does not mean you have bad credit. A 690 FICO score remains within the good category and may provide access to a wide range of credit products.
The national average is useful for comparison, but it is not a minimum requirement for borrowing. Lenders evaluate each application using their own eligibility rules and risk assessment methods.
Your goal should be to maintain a positive credit history and improve your financial position rather than focusing only on the national average.
690 Credit Score vs. 700, 720, 740, and 780
A 690 score is already good, but moving into a higher range may strengthen your borrowing position.
| Credit Score | FICO Category | General Meaning |
| 690 | Good | A solid credit position |
| 700 | Good | Higher within the good range |
| 720 | Good | A stronger good-range score |
| 740 | Very Good | Enters the very good category |
| 780 | Very Good | Toward the upper end of very good |
The difference between 690 and 740 is important because 740 enters the very good FICO category. A higher score may help you qualify for more favorable rates and financial products, depending on the lender.
However, no score guarantees approval or the lowest interest rate. Lenders also consider your debt, income, credit history, and the type of financing you are requesting.
Common Mistakes to Avoid With a 690 Credit Score
Maintaining a good credit score requires consistent financial habits. Certain mistakes can cause unnecessary damage to your credit profile.
Missing payment deadlines: A single missed payment can hurt your credit history. Use reminders or automatic payments to stay organized.
Using too much available credit: High credit card balances can increase utilization and negatively affect your score. Keep balances manageable.
Applying for several credit products: Multiple hard inquiries may temporarily lower your score. Avoid applications that do not support a genuine financial need.
Closing accounts without planning: Closing a credit card can reduce your available revolving credit. Consider its fees, age, and impact on utilization before making a decision.
Ignoring credit report errors: Incorrect account information can affect your borrowing opportunities. Review your reports and dispute genuine mistakes.
Carrying unnecessary debt: You do not need to borrow money or pay interest to maintain a good score. Use credit only when it makes financial sense.
Conclusion
A 690 credit score is good under both commonly used FICO and VantageScore classifications. It can help you qualify for credit cards, auto loans, personal loans, and certain mortgage programs. However, you may not receive the most competitive interest rates available to borrowers with very good or exceptional credit.
The best way to build on a 690 score is to maintain on-time payments, reduce credit card balances, keep utilization low, and avoid unnecessary applications. Reviewing your credit reports can also help you identify mistakes that may be affecting your score. Moving toward 720 or 740 could improve your financial opportunities over time. With consistent credit management, you can maintain a strong foundation and work toward even better borrowing terms.
Frequently Asked Questions
1. Is 690 a good credit score?
Yes, a 690 credit score is considered good under the standard FICO model and commonly used VantageScore models. It may help you qualify for different financial products, although the interest rate and approval decision depend on the lender.
2. Can I get a mortgage with a 690 credit score?
Yes, a 690 score may meet the credit requirements for several conventional and FHA mortgage programs. Approval also depends on income, debt-to-income ratio, down payment, property requirements, and lender-specific guidelines.
3. Can I get a car loan with a 690 credit score?
Yes, many auto lenders consider applicants with a 690 score. Your interest rate and loan conditions will depend on your complete financial profile, the vehicle, and the lender’s requirements.
4. How can I increase my 690 credit score to 740?
Pay your bills on time, reduce credit card balances, maintain low utilization, avoid unnecessary hard inquiries, and review your credit reports for errors. Consistent financial habits can help you move toward 740 over time.
5. Is a 690 credit score above the national average?
No. FICO reported an average U.S. credit score of 714 in July 2026. However, 690 is still considered good under FICO’s standard scoring ranges and may provide access to many financial products.